How to File an Insurance Claim
How to File an Insurance Claim is easier to understand when you focus on real decisions rather than confusing jargon. This guide explains what to check, what to document, and when it makes sense to ask a qualified professional for help. The goal is to help drivers make informed choices without promising outcomes that depend on vehicle condition, insurance coverage, or state law.
At 411 Collision, we believe clear information should come before a stressful decision. Whether you are getting ready for a trip or sorting out what happens after an accident, use the steps below as a practical starting point.
Make safety your first step
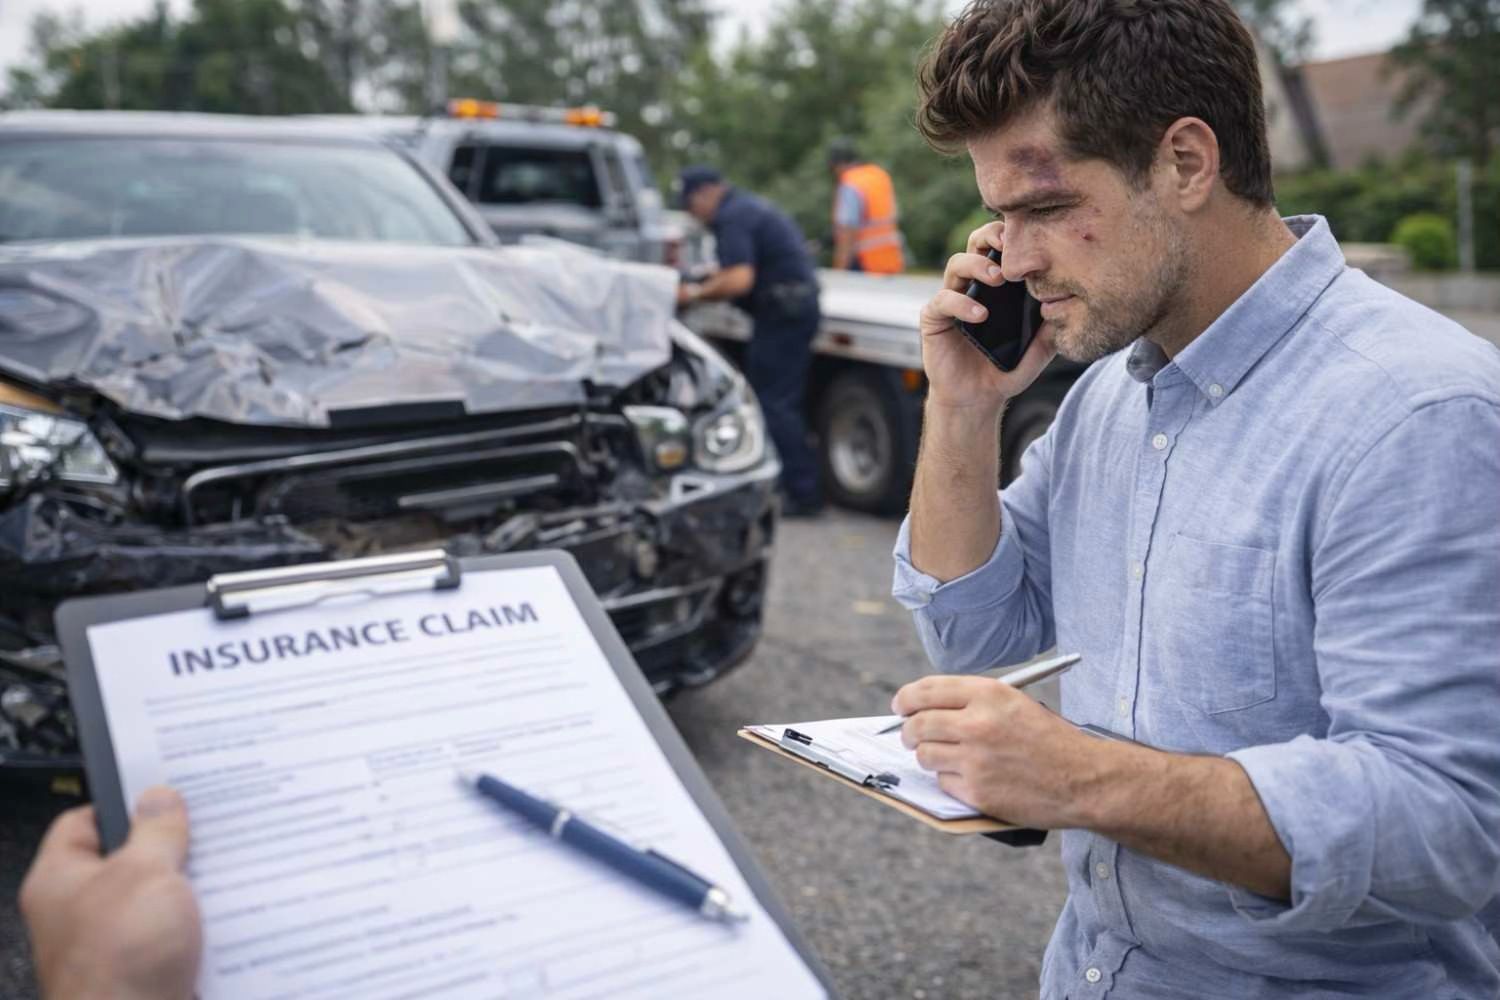
After a crash, check for injuries and call emergency services if needed. Move out of traffic when it is safe and legal to do so. Follow local reporting requirements. Never stand in a live lane to take photographs.
Collect useful information
Exchange names, contact details, driver and vehicle information, license plates, and insurer details. Photograph vehicle positions, damage, road conditions, signs, and relevant debris when safe. Note witnesses and the time and location.
Quick actions
- Write down what you noticed and when it began.
- Take clear photographs when it is safe to do so.
- Ask for written findings and the next recommended step.
Notify the insurer promptly
Review the policy for notice requirements, deductibles, rental coverage, and preferred claim methods. Provide a factual account and the documentation you have. You do not need to guess about damage you cannot see or speculate about fault.
Understand the adjuster’s role
The adjuster reviews coverage, evidence, estimates, and applicable rules. An initial estimate may be preliminary. Hidden damage discovered during teardown may require a supplement and insurer review.
Choose a qualified repair facility
Ask about repair procedures, parts, calibrations, warranty terms, and communication during the job. In many situations you can choose a repair shop, although coverage and program rules vary. Do not authorize work you do not understand.
Quick actions
- Write down what you noticed and when it began.
- Take clear photographs when it is safe to do so.
- Ask for written findings and the next recommended step.
Track the claim in writing
Keep the claim number, adjuster contact, photos, estimates, receipts, rental invoices, and correspondence. Ask for written explanations of disputed charges or coverage decisions. This makes follow-up easier if the repair timeline changes.
Before you close the file
Review the final invoice and inspect the repaired vehicle. Ask whether safety systems were scanned or calibrated when required. Confirm your deductible, any remaining balance, and the process if a repair issue appears later.
Practical details worth remembering
A practical example
Imagine discovering a warning light the evening before a long drive. It may be tempting to ignore it because the vehicle still runs, but the better approach is to check the owner’s manual and obtain a diagnosis when the warning suggests a safety or reliability concern. A short delay at home is usually easier to manage than a breakdown far from familiar services.
For how to file a car insurance claim, the useful question is not simply “what usually happens?” but “what does the evidence show in this particular situation?” Vehicle history, conditions, and timing can change the answer. If something is unclear, ask for an explanation in plain language and note the answer for future reference.
What to ask a professional
Ask what was inspected, which findings are urgent, what can reasonably wait, and whether any manufacturer procedure applies. Request written documentation. Clear questions make it easier to compare recommendations and avoid confusion about what the vehicle needs.
For how to file a car insurance claim, the useful question is not simply “what usually happens?” but “what does the evidence show in this particular situation?” Vehicle history, conditions, and timing can change the answer. If something is unclear, ask for an explanation in plain language and note the answer for future reference.
Common mistakes to avoid
One frequent mistake is assuming that a quick visual check tells the whole story. Another is waiting until the last minute, when parts or appointments may not be available. Give yourself time to address a concern, review the paperwork, and make a practical decision.
For how to file a car insurance claim, the useful question is not simply “what usually happens?” but “what does the evidence show in this particular situation?” Vehicle history, conditions, and timing can change the answer. If something is unclear, ask for an explanation in plain language and note the answer for future reference.
Keep records that matter
Store dated photographs, invoices, service history, and written communications in one folder. Good records help you remember what happened and can be useful if a repair, warranty, or insurance question arises later. Include the vehicle identification number when appropriate.
For how to file a car insurance claim, the useful question is not simply “what usually happens?” but “what does the evidence show in this particular situation?” Vehicle history, conditions, and timing can change the answer. If something is unclear, ask for an explanation in plain language and note the answer for future reference.
When circumstances change
Conditions can shift after the original plan or estimate. Weather may worsen, damage may become more apparent, or an insurer may request more documentation. Reassess using the latest information rather than relying on an earlier assumption.
For how to file a car insurance claim, the useful question is not simply “what usually happens?” but “what does the evidence show in this particular situation?” Vehicle history, conditions, and timing can change the answer. If something is unclear, ask for an explanation in plain language and note the answer for future reference.
A final decision checklist
Before moving forward, confirm the safety issue, the responsible contact, the expected next step, and any deadline. Ask for clarification when terminology is unfamiliar. A careful decision is not always the fastest one, but it is easier to defend and follow up.
For how to file a car insurance claim, the useful question is not simply “what usually happens?” but “what does the evidence show in this particular situation?” Vehicle history, conditions, and timing can change the answer. If something is unclear, ask for an explanation in plain language and note the answer for future reference.
Putting the advice into practice
In practice: Make safety your first step
Take a moment to apply this point to your own vehicle. After a crash, check for injuries and call emergency services if needed. Move out of traffic when it is safe and legal to do so. Follow local reporting requirements. Never stand in a live lane to take photographs. A useful next step is to record the date, note any symptoms or questions, and decide whether the matter calls for an inspection, a phone call, or simply an item on your pre-trip checklist. Do not rely on assumptions about another driver’s experience; the same visible symptom can have more than one cause.
In practice: Collect useful information
Take a moment to apply this point to your own vehicle. Exchange names, contact details, driver and vehicle information, license plates, and insurer details. Photograph vehicle positions, damage, road conditions, signs, and relevant debris when safe. Note witnesses and the time and location. A useful next step is to record the date, note any symptoms or questions, and decide whether the matter calls for an inspection, a phone call, or simply an item on your pre-trip checklist. Do not rely on assumptions about another driver’s experience; the same visible symptom can have more than one cause.
In practice: Notify the insurer promptly
Take a moment to apply this point to your own vehicle. Review the policy for notice requirements, deductibles, rental coverage, and preferred claim methods. Provide a factual account and the documentation you have. You do not need to guess about damage you cannot see or speculate about fault. A useful next step is to record the date, note any symptoms or questions, and decide whether the matter calls for an inspection, a phone call, or simply an item on your pre-trip checklist. Do not rely on assumptions about another driver’s experience; the same visible symptom can have more than one cause.
In practice: Understand the adjuster’s role
Take a moment to apply this point to your own vehicle. The adjuster reviews coverage, evidence, estimates, and applicable rules. An initial estimate may be preliminary. Hidden damage discovered during teardown may require a supplement and insurer review. A useful next step is to record the date, note any symptoms or questions, and decide whether the matter calls for an inspection, a phone call, or simply an item on your pre-trip checklist. Do not rely on assumptions about another driver’s experience; the same visible symptom can have more than one cause.
In practice: Choose a qualified repair facility
Take a moment to apply this point to your own vehicle. Ask about repair procedures, parts, calibrations, warranty terms, and communication during the job. In many situations you can choose a repair shop, although coverage and program rules vary. Do not authorize work you do not understand. A useful next step is to record the date, note any symptoms or questions, and decide whether the matter calls for an inspection, a phone call, or simply an item on your pre-trip checklist. Do not rely on assumptions about another driver’s experience; the same visible symptom can have more than one cause.
Frequently asked questions
How early should I prepare?
A week or more before a major trip is ideal for routine checks, with extra time if repairs or parts may be needed.
Can I drive if the car looks fine?
Appearance alone cannot confirm safety after a collision or when a warning light is on. A qualified inspection may be needed.
Will insurance pay for everything?
Coverage, deductibles, limits, fault rules, and state requirements differ. Review your policy and request a written explanation.
What should I bring to a body shop?
Bring the claim number if available, insurer contact information, photographs, and any estimate or repair paperwork.
How can I avoid delays?
Respond promptly to document requests, keep copies, and ask who is responsible for the next decision.
Talk with 411 Collision
Need help understanding collision damage or planning your next step after an accident? Contact 411 Collision to discuss your concerns and ask about an inspection or estimate. We can help you understand the repair process; your insurer determines coverage and payment.
